

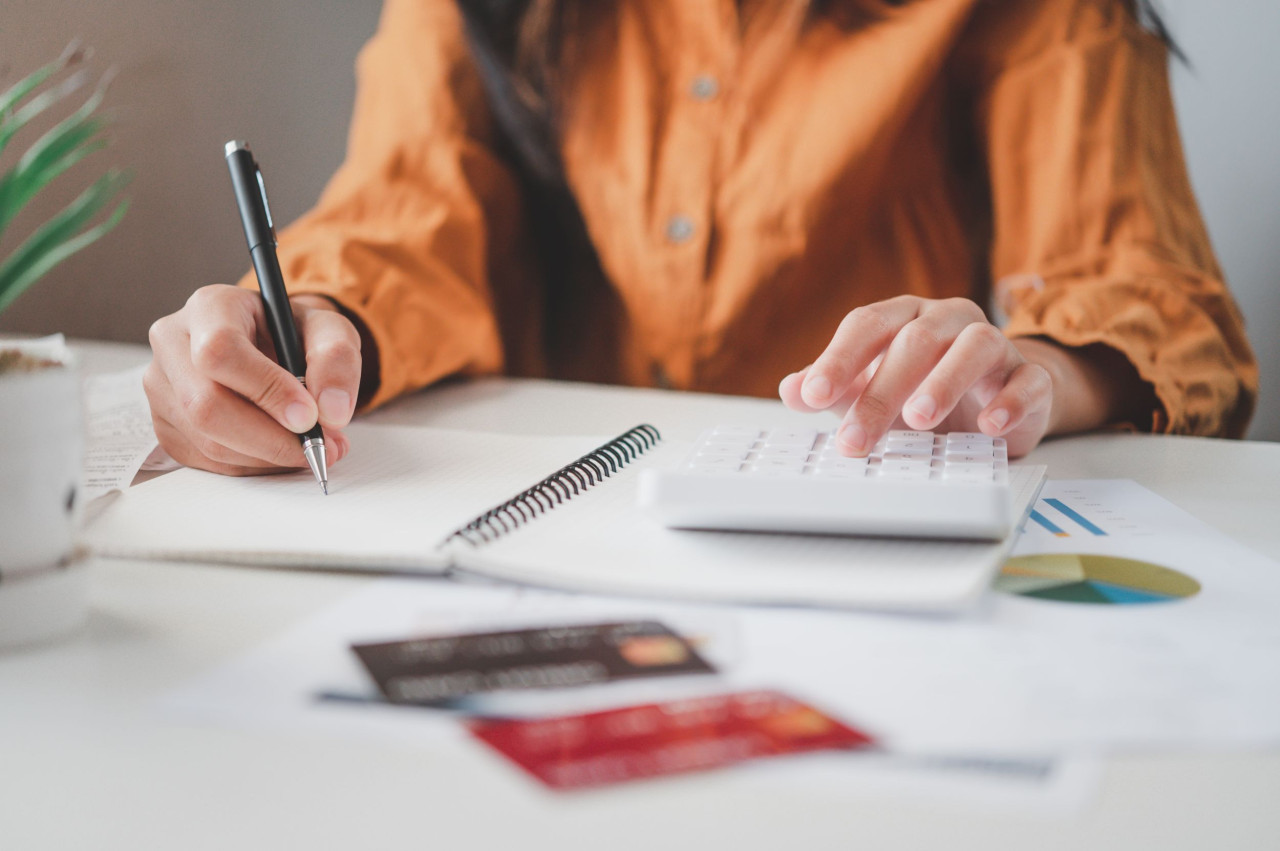
Credit card: how much does paying only the minimum cost?
Pay only the minimum on the card to ease the budget, but it has a price. We do the math in euros to show how much more you pay in interest and how long it takes to clear the debt.
20 nov 2026 • 4 min


November and December are the months when the credit card works the most: Black Friday, gifts, Christmas dinners. In January, the statement arrives, and the "minimum payment" option seems like a help.
Minimum payment avoids default but doesn't resolve debt. In this article, we show, with a concrete example, how long and how much money it costs to pay only the minimum, and how to get out of this spiral.
How does the minimum payment work
The minimum payment is the smallest amount you must pay every month to avoid default. It is usually a percentage of the outstanding balance, with a fixed minimum value.
The problem is in the math: a large part of this payment goes to interest. As the balance drops slowly, the minimum also drops, and the debt drags on for years.
Example: 1,500 euros on the card
Imagine you arrive in January with 1,500 euros in credit card debt, at a 16% annual interest rate, and stop using the card.
| How to pay | Time to settle (approx.) | Total paid (approx.) | Interest paid (approx.) | Total paid (approx.) | Interest paid (approx.) |
| Only the minimum (3% of balance, minimum 25 €) | 6 years and a half | $2 300,00 | €800,00 | €2 300,00€ | €800,00 |
| Only the minimum (5% of balance, minimum 25 €) | 4 years and a half | $1,940.00 | €440,00 | €1 940,00 | €440,00 |
| Fixed value of 100 € per month | 17 months | €1 685,00 | €185,00 | €1 685,00 | €185,00 |
| Fixed value of 150 € per month | 11 months | $1 620,00 | €120,00 | €1 620,00 | €120,00 |
Values are illustrative only. The rate, percentage, and minimum amount vary by contract. Check your statement and card agreement.
Paying only the minimum can turn Christmas purchases into a debt lasting until 2033.
3 ways to leave faster
1. Pay a fixed amount above the minimum
Choose an amount that fits your budget and pay it every month, even when the minimum decreases. As shown in the table, the interest difference is huge.
Use the Christmas allowance or the extra money from November
The Christmas allowance and the tax retention break in November are good opportunities to reduce the card balance. Few apps offer such a guaranteed "return" as avoiding 16% interest.
3. Consolidate debt into a loan with a lower rate
If you have balance on several cards or other consumer credits, you can combine them into one payment. With a lower rate and a defined term, you know exactly when the debt ends. Read also "Consolidated credit: how to know if the payment reduction is worth the total cost?"
How to avoid returning to the same point
• Use the card only for purchases you can pay in full by the due date.
• Enable full automatic payment, if your bank allows it.
• Lower the card limit to a value you can control.
• Create an emergency fund so unexpected expenses don't go to the card.
Swap your credit card debt for a payment with a clear end.
If the card (or cards) is weighing on the budget, simulate consolidation and see how much you can save on interest and when you'll be debt-free. The experts at Poupança no Minuto handle everything for you. Get a personalized analysis, no cost or commitment.
FAQ
Does paying the minimum on the card affect my credit history?
Pay the minimum on time to avoid default. But a high and persistent balance increases your credit responsibilities, which may affect new applications.
What is the interest rate of a credit card?
Varies by contract and is subject to maximum limits defined quarterly by Banco de Portugal. Confirm the TAN and TAEG on your statement.
Can I include a credit card in a consolidation loan?
Yes, credit card balances are usually included, according to each institution's solution and your profile analysis.
Should I cancel the card after paying off the debt?
Not required. If you keep it, lower the limit and use it only for purchases you pay in full each month.
Did you enjoy reading? Share it!
Related Articles
Cartão de crédito: quanto custa pagar só o mínimo?

4 min
Crédito pessoal ou cartão de crédito: Qual escolher?
2 min
Gerir um orçamento familiar? Conheça a regra de poupança 50/30/20
3 min
Resgatar PPR em 2026: Guia de regras, isenções e impostos
3 min
Want to save on credits and insurance?
Subscribe to our newsletter and never miss any content. Learn how to have a healthier financial life.

Talk to an agent now
Want to know more? Talk to one of our agents to clarify any doubts and discover the perfect solution for you.
Call to national landline | Monday to Friday, 9am to 7pm.